A real estate agent in Toronto is preparing to submit an offer for a first-time homebuyer. The buyer has received mortgage pre-approval, but several questions remain about financing conditions, documentation, and what happens after an offer is accepted.
The agent needs a mortgage professional who can explain these concerns accurately, respond when necessary, and guide the buyer through the appropriate financing process.
At that moment, the agent is unlikely to choose a mortgage broker simply because they have an impressive Instagram following or have sent several promotional emails. They want confidence that the professional they introduce to their client will deliver a reliable experience.
This is the foundation of learning how to market to realtors as a mortgage broker. Successful referral relationships are built by demonstrating expertise, understanding the agent’s responsibilities, and creating a dependable process for helping shared clients.
In Canada, mortgage referral marketing also requires careful consideration of client consent, professional independence, brokerage policies, and provincial regulatory requirements. An effective partnership should never depend on pressuring consumers toward a particular provider or promising financial outcomes that cannot be guaranteed.
At SuperKreatives, we approach realtor referrals as a structured business development opportunity rather than a simple exchange of contacts.
This guide explains how Canadian mortgage brokers can identify suitable real estate partners, introduce themselves professionally, develop useful collaboration opportunities, create a referral management system, and measure results without compromising borrower trust.
Why Realtor Referrals Matter to Canadian Mortgage Brokers
Buying a property involves several decisions that connect real estate services with mortgage financing.
A real estate professional may help clients understand the property search, offer conditions, transaction coordination, and purchase process. A mortgage broker helps borrowers navigate the financing process within their professional role.
Because these activities are connected, relevant professional introductions can be useful.
A buyer may need to speak with a mortgage broker before making an offer. Another buyer may require additional financing guidance after finding a property. A real estate professional may also encounter clients whose circumstances warrant specialized mortgage advice.
The value of the relationship is not simply that an agent knows people who want to buy homes. It is that the professionals can help clients understand different parts of a complicated transaction.
What Canadian Mortgage Consumer Research Tells Us
The Canada Mortgage and Housing Corporation’s (CMHC) 2026 Mortgage Consumer Survey asked more than 4,100 recent Canadian mortgage consumers about their experiences.
Among homebuyers, 32% identified real estate agents as the most valued individuals in their homebuying decision, while 24% selected mortgage brokers.
The results reinforce the important but distinct roles these professionals play during property purchases.
CMHC’s 2024 Mortgage Consumer Survey also reported that recommendations or reputation were cited by 30% of mortgage broker users as a main reason for choosing a broker, compared with 12% of direct lender users. These figures describe the surveyed consumers’ stated reasons, not the percentage of mortgage business generated specifically by realtor referrals.
Together, these findings support a practical observation: professional trust and recommendations can influence mortgage consumer decisions.
They do not establish that every real estate partnership will produce referrals or that mortgage brokers should rely exclusively on this acquisition channel.
A brokerage still needs effective client service, accurate financial communication, and other marketing channels.
Mortgage Referral Marketing: Understand What Real Estate Agents Actually Need
The most common mistake in referral marketing is focusing immediately on what the mortgage broker wants.
A broker wants qualified introductions, applications, and funded transactions. But the real estate agent has different immediate concerns.
They want clients to receive appropriate professional guidance, understand financing-related responsibilities, and experience reliable communication when important transaction questions arise.
Marketing should begin with those concerns.
Reliability Matters More Than Promotional Claims
A mortgage broker who repeatedly promises the lowest rates may attract attention, but that claim does little to demonstrate how they will handle a real client’s financing questions.
A more persuasive professional introduction explains the services offered, the types of borrowing circumstances the broker works with, and the process for managing enquiries.
For example, an agent serving first-time buyers may value a mortgage professional who can explain pre-approval limitations and common documentation requirements.
An agent regularly working with self-employed purchasers may appreciate access to someone knowledgeable about relevant income assessment considerations.
The mortgage professional should demonstrate genuine competence rather than promise universal approval or exceptional results.
Agents Need Clear Boundaries Around Financing Advice
Real estate professionals and mortgage professionals have different responsibilities.
A real estate agent can recognize when financing questions arise, but they should not be encouraged to make mortgage qualification decisions beyond their permitted role.
A broker can support agents by explaining general financing processes, identifying common misconceptions, and being available for appropriate borrower consultations.
This helps both professionals serve the client without confusing their responsibilities.
Borrowers Must Remain Free to Choose Their Mortgage Provider
A professional relationship should not result in consumers being pressured to work with a particular brokerage.
For example, British Columbia’s Financial Services Authority advises real estate professionals to provide clients with a choice of service providers, recommending a list of at least three when making such referrals.
This guidance reflects the importance of independent consumer choice.
A mortgage broker should therefore position themselves as a suitable professional option, not as someone entitled to every buyer represented by a particular agent.
8 Practical Ways to Build Realtor Referral Relationships
Developing a referral network requires consistent professional activity, but it does not have to involve complicated campaigns.
The most productive starting point is identifying professionals whose clients align with the brokerage’s actual services.
1. Identify Realtors Who Work With Your Ideal Borrowers
A mortgage broker serving first-time homebuyers may benefit from relationships with agents active in entry-level residential markets.
Someone with expertise in investment property financing may find greater relevance among professionals who regularly assist property investors.
Likewise, brokers working with self-employed applicants may find opportunities to educate agents about financing considerations for business owners.
The objective is not to contact as many real estate professionals as possible.
It is to find appropriate business relationships where the mortgage broker’s knowledge can genuinely support the agent’s clients.
Research relevant professionals using their public business websites, licensed brokerage information, professional profiles, and actual areas of service.
Avoid assuming that an agent has particular transaction volumes, client financial characteristics, or referral potential without evidence.
2. Introduce Yourself With a Specific Professional Value
Generic outreach rarely gives someone a compelling reason to respond.
A message saying “I’m a mortgage broker, please send me referrals” explains what the sender wants but provides little value to the recipient.
A stronger introduction identifies the broker’s area of expertise and offers a relevant professional conversation.
For example:
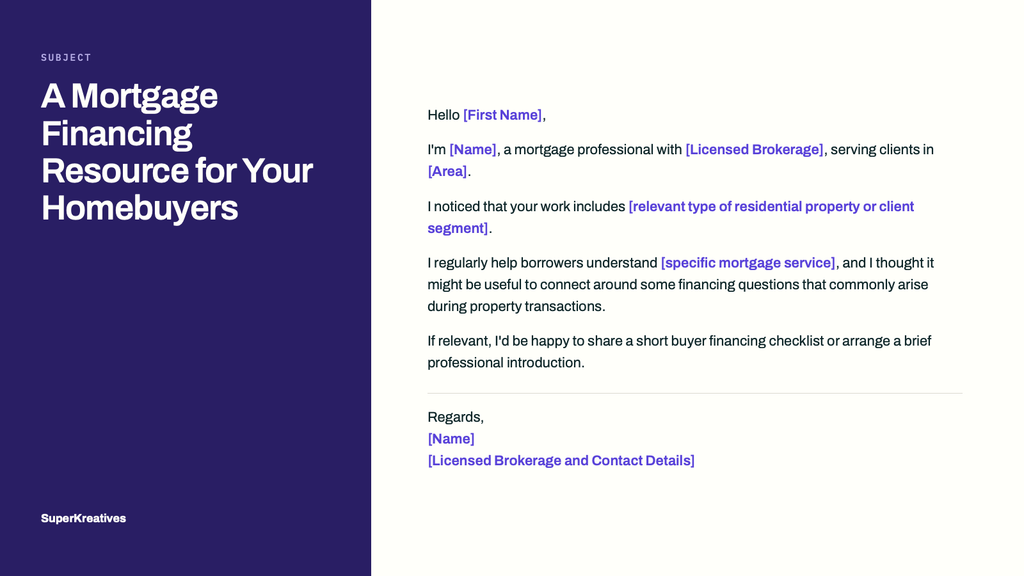
This message should be customized using verified information, not assumptions.
Commercial email outreach also needs a valid basis under Canada’s Anti-Spam Legislation (CASL), as discussed later in this guide.
3. Offer a Financing Education Session
Educational sessions are among the most credible ways for mortgage brokers to introduce their expertise.
A real estate office might benefit from a discussion about the differences between pre-approval and final approval, common mortgage documentation requirements, or financing conditions during a property purchase.
The presentation should focus on practical questions agents encounter rather than becoming an extended sales pitch.
For example, a session about pre-approval could explain why final financing may still depend on lender review, updated borrower information, property characteristics, and outstanding conditions.
The material should distinguish general education from advice about any individual buyer’s eligibility.
This provides genuine professional value even when the session doesn’t result in immediate referrals.
4. Develop a Buyer Financing Checklist Agents Can Share
A practical checklist can help prospective buyers prepare for conversations with a licensed mortgage professional.
It might explain common preparation topics such as income information, existing debt obligations, down payment planning, and expenses beyond the purchase price.
The resource should avoid presenting the checklist as a guarantee that completing each step will result in financing approval.
A useful checklist also explains when a buyer should request individualized mortgage guidance.
Provide a digital version that agents can share when appropriate, together with accurate brokerage identification and contact information.
This creates a reusable educational resource without requiring agents to make financial recommendations themselves.
5. Create Co-Branded Videos and Educational Content
Marketing opportunities for real estate agents and mortgage brokers often emerge where both professions contribute to a shared consumer question.
For example, a short video could explore what buyers should understand before submitting a property offer.
The agent might explain the general offer process, while the mortgage broker discusses the limitations of pre-approval and the need to confirm relevant financing details.
Other suitable subjects include closing-cost preparation, first-time homebuyer questions, and common misunderstandings about financing conditions.
The content should clearly identify each professional and their respective responsibilities.
Where required, both brokerages should review the content and approve relevant branding, licensing information, and financial statements.
Co-marketing should not imply that consumers are required to use either professional to access the other’s services.
6. Participate in Appropriate Buyer Workshops and Events
Local education events can introduce mortgage professionals to both real estate agents and prospective borrowers.
A first-time buyer workshop in Calgary could explain the different stages of a home purchase, with each professional contributing within their expertise.
A session in Ottawa might focus on preparing for financing conversations before making an offer.
Events should communicate what attendees will learn rather than advertise unrealistic mortgage outcomes.
If registrations collect contact details, explain who is collecting that information, how it will be used, and whether attendees are subscribing to future promotional communication.
7. Maintain Professional Contact Without Constantly Requesting Leads
A relationship doesn’t become valuable simply because two professionals exchange business cards.
Relevant follow-up helps maintain familiarity.
This might involve sharing an accurate explanation of an important mortgage development, inviting an interested agent to an educational event, or discussing general financing questions when appropriate.
However, communication should reflect the relationship and the recipient’s preferences.
Sending repeated promotional requests to people who haven’t shown interest is unlikely to improve professional confidence.
The goal is to become a knowledgeable contact whose communications are worth receiving.
8. Deliver a Reliable Experience When a Referral Occurs
The most important stage begins after a borrower decides to speak with the mortgage broker.
The brokerage should acknowledge the enquiry, explain the consultation process, and respond consistently.
Where the buyer has authorized communication with the real estate agent, appropriate process updates may help coordinate the transaction.
However, the agent does not automatically gain access to private financial documents, credit information, or lender assessments merely because they made the introduction.
Professional reliability, confidentiality, and accuracy should take priority over maintaining the appearance of constant activity.
A positive borrower experience provides a stronger foundation for future professional relationships than repeated requests for additional referrals.
Mortgage Realtor Marketing: Build a Partnership Around Shared Educational Value
An effective partnership should have a clear purpose beyond introducing contacts.
For example, a mortgage broker and real estate professional could collaborate on a first-time homebuyer information series.
The agent explains the property search and transaction process. The broker explains the mortgage financing considerations.
Each piece of content can answer a question that overlaps with their responsibilities.
A useful approach is to organize collaboration into three categories.
Buyer preparation: Educational content covering pre-approval, purchase expenses, financing conditions, and general transaction readiness.
Professional education: Resources for agents addressing mortgage terminology, common documentation questions, and circumstances requiring specialized lending guidance.
Community education: Seminars, webinars, or online resources intended to help prospective homeowners understand the overall buying process.
These initiatives should be selected according to the audience, not simply produced because two businesses want to feature their logos together.
Mortgage Lender Realtor Marketing: A Different Partnership Model
Mortgage lenders may also develop professional relationships with real estate agents, but the marketing approach can differ from that of an independent brokerage.
A lender usually promotes its own mortgage products, application process, and eligibility requirements.
A broker may explain a wider range of financing options where available through their brokerage relationships.
For lender representatives, useful professional education could include product-specific documentation requirements, application procedures, or general explanations of financing features.
However, promotional materials should not suggest that a product is available to every borrower or that all applications will be approved.
The distinction between broker and lender services should remain clear to real estate professionals and borrowers.
How to Create a Mortgage Sales Referral Marketing System
Building relationships is only one part of referral development. A brokerage also needs a reliable process for managing legitimate introductions.
Without a structured system, one person might receive an introduction through LinkedIn, another through email, and a third through a phone call. Staff may struggle to identify who is responsible for responding or whether the referred borrower has agreed to be contacted.
A simple referral management process reduces these problems.
Define What Happens After an Introduction
A referral should begin with appropriate client authorization.
The real estate professional might introduce the buyer directly to a mortgage broker and let the borrower decide whether to initiate contact.
Alternatively, with suitable permission, the agent may facilitate an introduction using an agreed process.
Once the enquiry arrives, the brokerage should assign it to the appropriate mortgage professional and explain the next steps.
Any relevant referral compensation or disclosure requirements should be handled through the licensed businesses.
The 6-Step Mortgage Realtor Referral Framework
A successful mortgage referral programme needs more than occasional networking. It requires a structured process that helps mortgage brokers develop professional relationships, manage client introductions, and maintain consistent communication.
Step 1: Identify Relevant Real Estate Professionals
Start by identifying real estate agents whose clients align with your mortgage services. Focus on shared service areas, buyer segments, and financing needs rather than building a large, unfocused contact database.
Step 2: Demonstrate Professional Value
Before requesting referrals, establish credibility through educational resources, financing workshops, and practical conversations. Help agents understand common mortgage challenges their clients may encounter.
Step 3: Establish a Responsible Referral Process
When an agent identifies someone who may benefit from mortgage assistance, obtain appropriate client authorization before sharing personal information. Explain the introduction process and any applicable disclosure obligations.
Step 4: Provide a Reliable Consultation Experience
Once a referral arrives, acknowledge the enquiry, identify the responsible mortgage professional, and explain the next steps. Ensure that prospective borrowers receive relevant information without unrealistic financing promises.
Step 5: Maintain Appropriate Communication
Keep the referring professional informed about relevant transaction milestones only when the client has authorized such communication. Protect confidential financial information throughout the process.
Step 6: Measure Referral Quality and Relationship Performance
Track meaningful professional interactions, consented client introductions, qualified consultations, mortgage applications, and funded transactions. Use these insights to identify which relationships provide genuine value to borrowers and the brokerage.
A consistent referral framework helps mortgage professionals improve their business development process without reducing partnerships to a simple exchange of leads.
Use a CRM to Track Professional Relationships
A CRM helps organize professional contacts and relevant interactions.
Useful fields may include the real estate professional’s name, brokerage, service area, preferred communication method, professional interests, and the history of legitimate collaboration.
The brokerage can also track referred enquiries and their outcomes using appropriate access controls.
However, the CRM should not become an unrestricted source of confidential borrower information available to every referral partner.
A practical system distinguishes information about the professional relationship from the personal financial information of the borrower.
Establish Appropriate Follow-Up Responsibilities
Someone should be responsible for acknowledging each permitted introduction and ensuring the client understands the next step.
An internal reminder can flag enquiries that have not received attention.
If the client schedules a consultation, the status should update so unnecessary reminders stop.
A brokerage can also record when a referral cannot be served because the request falls outside its services or jurisdiction.
This creates a more accurate picture of the partnership’s relevance.
Mortgage Referral Statistics, Loan Officer Databases, and Marketing Measurement
Mortgage referral statistics should be used carefully, especially when online articles mix Canadian mortgage consumers with US loan officer and real estate data.
The phrase mortgage referral statistics loan officer database marketing combines several different research questions: how consumers discover providers, how mortgage professionals manage referral contacts, and how referral programmes perform.
They should not be treated as one dataset.
What Verified Referral Data Actually Shows
The 2026 Zillow Consumer Housing Trends Report found that 20% of surveyed US mortgaged homebuyers first found their lender through a real estate agent, REALTOR, or broker referral.
That is useful evidence that professional introductions play a role in the US mortgage market.
However, Zillow’s research is not a Canadian referral benchmark. The figure should not be used to predict how many borrowers a mortgage brokerage in Edmonton, Vancouver, or Toronto will acquire.
For Canadian planning, CMHC’s mortgage consumer surveys provide more relevant context about professional influence and borrower decisions.
The most useful business-specific statistics will usually come from the brokerage’s own CRM.
Which Referral Metrics Should Mortgage Brokers Track?
| Metric | What it reveals |
| Relevant professional contacts | Size of the appropriately targeted relationship network |
| Meaningful professional conversations | Whether introductions develop into actual engagement |
| Educational collaborations | Participation in relevant meetings, events, or resources |
| Consented borrower introductions | Number of eligible potential client referrals |
| Qualified consultations | Whether referrals match the brokerage’s services |
| Mortgage applications | Whether consultations progress to formal assessment |
| Funded mortgages | Completed business attributable to the referral source |
| Repeat referrals | Whether professional relationships remain active |
For example, imagine a brokerage establishes 25 suitable real estate contacts during an initial campaign.
Of these, eight engage in meaningful professional conversations, four eventually make appropriate client introductions, and three introductions result in qualified consultations.
The results may provide an early indication of which relationships deserve attention, but they do not establish a universal conversion benchmark.
Mortgage transactions also take time to progress, so funded mortgage results may become visible later.
Why Buying a Realtor Contact Database Is Not a Referral Strategy
A database of real estate professionals may help with research, but possessing names and email addresses does not establish a professional relationship.
It also does not create automatic permission for unrestricted commercial electronic messages.
A brokerage considering third-party prospect lists should verify the origin of the information, the permitted uses, accuracy, and applicable communication rules.
A smaller number of relevant relationships is often a more practical starting point than large-scale outreach with generic messages.
The aim is not to collect thousands of contacts. It is to establish trusted professional connections with people whose clients may benefit from your services.
Canadian Rules for Mortgage Referral Marketing
Referral activity can create legal and professional obligations, particularly when it involves financial benefits, client information, or mortgage-related advice.
These requirements differ by province, so a marketing strategy should not assume one national rule applies to every arrangement.
Ontario: Compensation, Conflicts, and Disclosure
Ontario’s Financial Services Regulatory Authority of Ontario (FSRA) explains that certain simple referrals by unlicensed individuals or businesses can fall within an exemption.
A simple referral generally involves passing along contact information rather than participating in arranging a mortgage.
However, more involved mortgage activities can require licensing.
FSRA also requires relevant remuneration, financial benefits, conflicts of interest, and other prescribed information to be disclosed according to applicable requirements.
Payments between licensed mortgage brokerages have specific rules and must be handled through the brokerages rather than directly between individual brokers or agents.
For a mortgage broker working with an Ontario real estate professional, a proposed compensation arrangement should be reviewed by the relevant brokerages before any commitments are made.
British Columbia: Explicit Consent and Referral Records
British Columbia’s BC Financial Services Authority (BCFSA) published mortgage referral guidance in December 2025 under the Mortgage Services Act framework.
The guidance states that mortgage referrals require the client’s explicit consent and must not involve unlicensed individuals arranging mortgages.
It also describes requirements for recording referral-related payments and disclosing relevant benefits.
These obligations should be considered before creating referral fees, rewards, or other financial arrangements.
Alberta: Financial Benefits and Client Information
Alberta’s Real Estate Council of Alberta (RECA) also addresses referral benefits and disclosure.
Its guidance identifies benefits that can include money, gifts, discounts, rewards, and other incentives.
The relevant rules also require licensees to protect confidential client information and address authorization for disclosure.
A mortgage professional serving Calgary or Edmonton should therefore obtain appropriate brokerage approval before introducing any compensated referral programme.
CASL: Professional Outreach and Email Marketing
Canada’s Anti-Spam Legislation generally requires a valid basis for consent, sender identification, and an unsubscribe mechanism for commercial electronic messages, subject to applicable exceptions.
The CRTC recognizes limited circumstances in which consent may be implied, including certain existing business relationships or appropriately published business email addresses when the message is relevant to the recipient’s role and there is no indication that commercial messages are unwanted.
There is also a narrowly defined exception for a first commercial electronic message following a qualifying referral. The exception has specific conditions, and identification and unsubscribe requirements still apply.
A mortgage broker should not treat a public LinkedIn profile or purchased contact list as unrestricted permission to launch automated promotional campaigns.
The stronger long-term approach is to develop partnerships around expertise and borrower service, then handle any financial arrangements through the appropriate compliance process.
A 90-Day Plan to Build Realtor Referral Relationships
A practical strategy should begin with a manageable number of relevant professional contacts rather than a large list of agents who may have little connection to the brokerage’s services.
| Timeline | Main objective | Recommended activity |
| Days 1–30 | Identify and introduce | Research suitable agents, prepare useful educational material, and establish appropriate introductions |
| Days 31–60 | Build professional value | Hold relevant conversations, offer educational sessions, and develop approved collaborative resources |
| Days 61–90 | Strengthen and measure | Establish referral handoff procedures, review engagement, and improve the relationship management process |
During the first month, prioritize service alignment. A mortgage professional experienced with first-time buyers should concentrate on relationships where that expertise is genuinely relevant.
The second month should focus on demonstrating knowledge and reliability. Useful financing resources and educational conversations are more meaningful than simply increasing outreach volume.
By the third month, evaluate whether the relationships have progressed beyond initial introductions.
Not every contact will produce a referral within 90 days. Professional confidence may develop over a much longer period, and a useful relationship can exist before any client introduction occurs.
Common Mistakes in Marketing Mortgage Services to Realtors
The first mistake is requesting referrals before establishing why the agent should trust the mortgage professional.
An agent needs confidence that a referred client will receive suitable professional assistance. Generic promotional claims rarely provide that assurance.
Another mistake is offering incentives without reviewing compensation and disclosure obligations. Financial arrangements that appear straightforward can create regulatory concerns when improperly structured.
Brokers should also avoid promising approval, particular rates, or guaranteed closing outcomes.
Mortgage eligibility depends on individual circumstances, lender requirements, documentation, and other considerations.
Finally, poor follow-up can undermine an otherwise promising relationship. A professional introduction creates an expectation of appropriate communication, but that communication must also respect the borrower’s privacy and consent.
Final Thoughts: Earn Realtor Referrals Through Professional Value
The most sustainable way to market a mortgage brokerage to real estate professionals is to make the relationship useful before expecting business from it.
Real estate agents want their clients to receive appropriate mortgage guidance. Mortgage brokers want to establish relationships with borrowers whose needs align with their services. An effective referral strategy helps connect these objectives without compromising consumer choice.
For Canadian mortgage professionals, this means identifying suitable partners, providing practical education, creating relevant collaborative resources, and maintaining dependable communication.
At SuperKreatives, we believe a referral programme should be evaluated through the quality of relationships and client outcomes, not merely the number of real estate professionals in a contact database.
Start with a focused group of suitable agents. Learn which financing questions matter to their clients, demonstrate how your expertise can help, and establish a respectful process for introductions.
When professional credibility, borrower consent, and consistent service guide the relationship, referral marketing can become a valuable part of long-term mortgage business development.
Frequently Asked Questions
How to market to realtors as a mortgage broker in Canada?
Begin by identifying real estate professionals whose clients align with your mortgage services. Introduce your expertise through relevant professional conversations, educational resources, and appropriate collaborations. Build trust through accurate financial explanations, consistent communication, and responsible client service rather than immediately requesting referrals.
What are effective marketing opportunities for real estate agents and mortgage brokers?
Useful opportunities include co-hosted homebuyer workshops, financing checklists, educational videos, professional webinars, and carefully reviewed co-branded resources. Each activity should provide genuine value to prospective borrowers and respect the professionals’ separate responsibilities.
Can mortgage brokers pay real estate agents referral fees?
Certain arrangements may be permitted, but requirements vary across Canada. Licensing, brokerage approval, compensation disclosures, client consent, and payment procedures can apply. Have any proposed referral compensation arrangement reviewed by the relevant brokerages and qualified compliance advisers before implementation.
How can mortgage brokers get referrals without paying commissions?
Mortgage professionals can develop relationships through financing education, professional networking, clear consultation processes, and reliable client experiences. A useful introduction should be based on the client’s needs and the professional’s suitability, rather than an expectation of compensation.
What should a mortgage broker track in a realtor referral CRM?
Track relevant professional contacts, approved communication preferences, meaningful interactions, consented referrals, consultation outcomes, and relationship history. Access to borrower financial information should remain appropriately restricted, and records should follow applicable privacy obligations.
Is mortgage lender realtor marketing different from broker marketing?
Yes. Lenders generally promote their own mortgage products and eligibility requirements, while brokers may assist borrowers in evaluating financing arrangements available through their brokerage. Educational and referral materials should accurately describe each professional’s role.
Are mortgage referral statistics from the United States useful in Canada?
They can provide background context but should not be treated as Canadian market benchmarks. Differences in lending systems, consumer behaviour, regulation, and professional relationships limit direct comparisons. Canadian mortgage research and the brokerage’s own CRM data are more relevant for planning.
How long does it take to build a mortgage realtor referral network?
There is no fixed timeline. Some relationships develop through existing professional connections, while others require repeated useful interactions before a referral occurs. Measure relationship quality, suitable introductions, and client outcomes rather than assuming referrals must appear within a particular number of weeks.